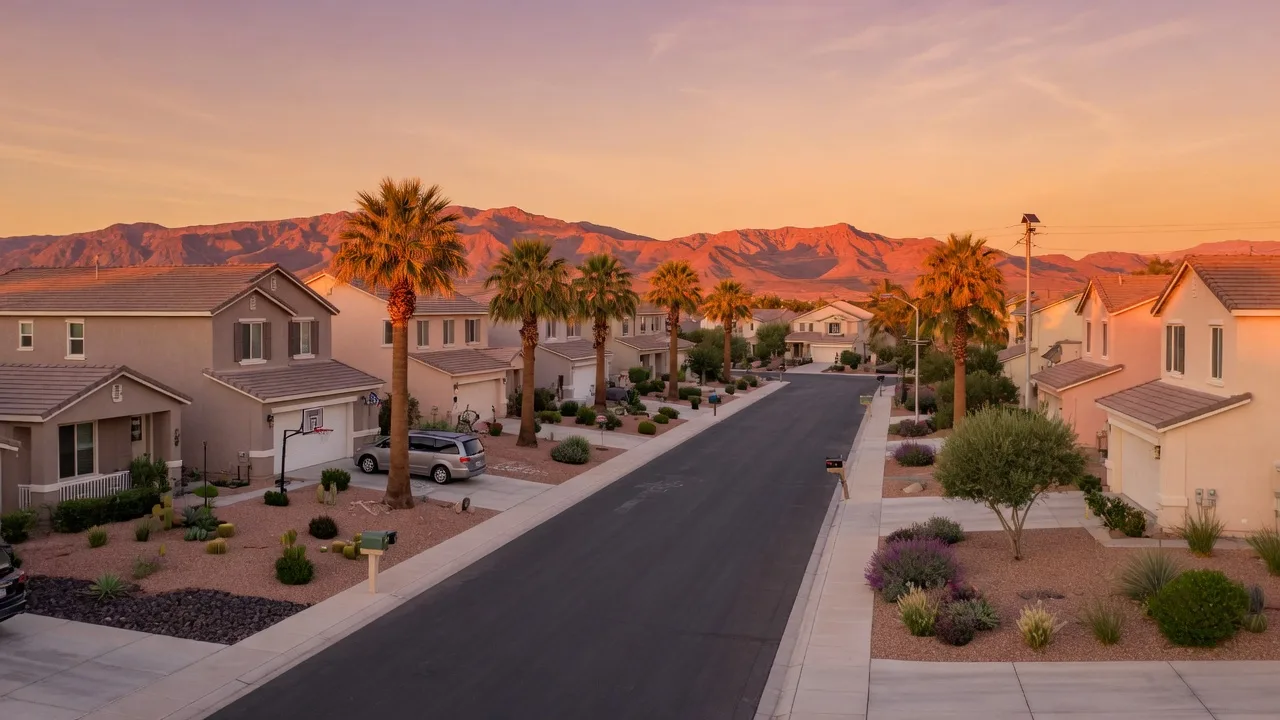
If you are thinking about buying your first home in the Las Vegas Valley, I have good news. The market right now is arguably the most favorable for first-time buyers that we have seen in years. That might sound surprising given the headlines about record-high median prices, but the numbers tell a more nuanced story -- and understanding that story is the first step toward making a confident, informed decision.
I know what it is like to wonder whether homeownership is within reach. I put myself through college as a single mother and learned firsthand that financial literacy and determination are more powerful than a big bank account. That is why I am passionate about helping first-time buyers understand not just the market, but the wealth-building opportunity that homeownership represents. Let me walk you through what the current market means for you.
The Market Is More Balanced Than It Has Been in Years
The biggest shift in the Las Vegas Valley market over the past 12 months has been the return of balance. Throughout 2021 and 2022, buyers faced a white-hot market with multiple offers, bidding wars, and inventory so tight that homes sold in days. Today, the valley has about three months of supply, which is firmly in balanced territory. That means buyers have time to shop, compare homes, and make thoughtful decisions instead of rushing into an offer.
For first-time buyers, this is a game changer. You can visit multiple homes, take notes, and sleep on a decision without worrying that the house will be gone by morning. You can ask questions, negotiate, and work with your agent to craft an offer that fits your budget and your comfort level. The pressure that defined the pandemic-era market is gone, and what has replaced it is a healthier, more sustainable environment for buyers.
At the same time, home prices have held at a record median of $490,000 for single-family homes. That is a positive sign for long-term stability. When prices hold steady rather than spiking or crashing, it means the market has found a genuine equilibrium between what buyers can afford and what sellers are willing to accept. That stability is the foundation that smart buyers build on.
Mortgage Rates Are Higher, but There Are Strategies to Manage Them
The biggest challenge for buyers right now is mortgage rates. Thirty-year fixed rates are hovering around 6.55 percent, which adds to monthly payments compared to the sub-3 percent rates of 2020 and 2021. But here is what I tell every buyer who asks about rates: you cannot time the market, and waiting for rates to drop while prices continue to climb can cost you more in the long run.
The good news is that there are proven strategies to make today's rates more manageable:
- Seller concessions are available in roughly 40% of deals. Many sellers in today's market are willing to contribute toward closing costs or offer a temporary rate buydown to make the deal work. A 2-1 buydown can reduce your rate by 2% in year one and 1% in year two, buying you time for rates to potentially come down before you refinance.
- Builder incentives are aggressive in new construction communities. Builders in Summerlin, Henderson, Northwest Las Vegas, and Mountain's Edge are offering rate buydowns, closing cost credits, and free upgrades to move inventory. I have seen deals that effectively lower the buyer's rate by a full point or more.
- You can refinance when rates drop. Every buyer I work with understands that buying now and refinancing later is an option. If rates drop to 5.5% or lower in the next year or two, refinancing could save you hundreds per month.
Nevada Has Powerful Down Payment Assistance Programs
One of the most underutilized resources for first-time buyers in the Las Vegas Valley is the range of down payment assistance programs available through the Nevada Housing Division. These programs are designed specifically to help buyers who have good income and solid credit but lack the cash for a large down payment. Let me walk you through the most impactful ones.
Home Is Possible (HIP) Standard provides up to 4 percent of the loan amount in down payment or closing cost assistance. On a $400,000 home, that is up to $16,000. The assistance is forgiven after three years, meaning you do not have to pay it back if you stay in the home. There is no first-time buyer requirement, and the minimum credit score is 640.
The Worker Advantage Program is one of the most powerful options available in 2026. It offers $20,000 in down payment assistance for essential workers including healthcare professionals, educators, first responders, construction workers, and casino employees. You need a 640 credit score, six months of Nevada residency, and a household income at or below 150 percent of the area median income. Importantly, you do not need to be a first-time buyer to qualify, and as of early 2026, significant funding was still available.
Other programs worth exploring include the Home First program ($15,000 in assistance, forgivable after three years), Home Is Possible for Teachers ($7,500), and the Home Is Possible for Heroes program for veterans, law enforcement, and firefighters. The Mortgage Credit Certificate program also provides a federal tax credit on mortgage interest, effectively lowering your tax bill each year.
Samantha's tip: Many buyers assume they cannot qualify for these programs, but the eligibility requirements are broader than most people think. I have helped buyers combine down payment assistance with conventional financing to buy a home with less than 5 percent cash out of pocket. The key is getting connected with a lender who understands these programs and structuring your offer strategically.
Where First-Time Buyers Are Finding Value in the Valley
Not every neighborhood in the Las Vegas Valley carries a $490,000 price tag. Here are the areas where I am seeing the strongest value for first-time buyers in mid-2026:
- North Las Vegas: The strongest year-over-year price growth in the valley at 6.6 percent, with a median around $385,000. Areas near Aliante and the growing northwest corridor offer new construction, good amenities, and some of the best price-to-value ratios in the valley.
- Southwest Las Vegas (Mountain's Edge area): A family-friendly master-planned community with homes typically ranging from the $360s to the $500s. The $43 million regional park expansion is adding serious long-term value, and the community's 3,500 acres offer excellent amenities for the price.
- Condos and townhomes: The condo and townhome segment has seen prices dip nearly 6 percent year-over-year while inventory has surged 24 percent. That means buyers in this segment have serious negotiating power. The median is around $292,000, and this is often the most affordable entry point into homeownership in the valley.
- Older neighborhoods in Henderson: Established communities like Green Valley offer single-family homes starting in the mid-$300s. The trade-off is older construction, but you gain mature landscaping, established schools, and a location that has already proven its long-term value.
The Real Cost of Waiting vs. Buying Now
One conversation I have frequently with first-time buyers is whether to wait for mortgage rates to drop or for home prices to soften. Here is what the data says. Home prices in the Las Vegas Valley have appreciated at roughly 1 to 4 percent annually over the past two years, which is a healthy, sustainable pace. A 3 percent increase on a $400,000 home means that same home costs $412,000 a year from now. Add in the equity you build through principal paydown over that year, and the math often favors buying now rather than waiting.
The other factor that matters is rent. The median two-bedroom apartment in the valley now rents for around $1,500 per month. Over a year, that is $18,000 in rent with nothing to show for it. A mortgage payment on a $350,000 home with 5 percent down and a 6.55 percent rate might be around $2,200 per month, but roughly $400 of that goes toward principal each month, which is money you are building for yourself. Over five years, that difference compounds significantly.
How to Start Your Homebuying Journey Today
The path to homeownership starts with information, not with a down payment. Here is how I guide every first-time buyer I work with:
- Get pre-approved with a lender who knows Nevada programs. Not all lenders understand down payment assistance or can structure the right loan. I have trusted partners I can connect you with.
- Understand your full budget. Your monthly payment is more than principal and interest. Property taxes, insurance, and HOA fees all factor in, and I will help you build a realistic picture.
- Define your must-haves and nice-to-haves. I will help you separate the features that truly matter from the ones you can compromise on, so we focus on homes that fit both your lifestyle and your budget.
- Tour neighborhoods, not just homes. The right community matters as much as the right house. I will take you through the areas that match your priorities so you can feel the difference firsthand.
I know that buying a home for the first time can feel overwhelming. I have been there myself, navigating life independently since I was fourteen and figuring out how to build financial security from the ground up. That experience taught me that the biggest barrier to homeownership is not a lack of money. It is a lack of clear, honest information. My job is to make sure you have that information and the confidence to act on it.
The Bottom Line
The Las Vegas Valley market in July 2026 offers a rare combination for first-time buyers: balanced inventory that gives you time to decide, seller and builder incentives that reduce your costs, and down payment assistance programs that make homeownership accessible with less cash upfront than most people realize.
The record median price of $490,000 is not a barrier. It is a sign of stability. Homes in this market hold their value, build equity over time, and provide the financial foundation that renting simply cannot match. Whether you are looking at a condo in the $290s, a townhome in a growing community like Mountain's Edge, or a single-family home in Northwest Las Vegas, the opportunities are real, and they are available right now.
I would love to help you take the first step. There is no pressure, no sales pitch, just a conversation about where you are and where you want to be. Let us sit down and talk about what homeownership could look like for you.
First-time budgets stretch further in certain ZIPs: Aliante and North Las Vegas (89084, 89030, 89031, 89032, 89081, 89086), Mountain's Edge (89178), and parts of Henderson (89002, 89012, 89014, 89015, 89044, 89052, 89074). Browse what fits your budget on my live search: Search homes in the Las Vegas Valley.
Let us talk about what homeownership could look like for you.
Whether you are pre-approved, pre-qualified, or just starting to explore your options, I will give you honest, clear guidance. No pressure, just the information you need to make a confident decision.