Your home is more than a place to live. It is the single most powerful wealth-building tool most of us will ever own. And right now, Las Vegas homeowners are sitting on historically strong equity positions.
Since 2021, Las Vegas Valley home values have appreciated substantially. The homeowner who bought at the median price in 2020 has seen their equity grow by more than $140,000. Nationally, the average homeowner gained $56,700 in equity over the past year alone, according to CoreLogic data.
But here is the truth I share with every client: equity does not build itself. In a balanced market, where home prices are holding steady rather than spiking, the most successful homeowners are the ones who take intentional steps to grow their equity. Whether you bought your home five years ago or five months ago, these strategies can help you build wealth faster.
First, What Is Home Equity and Why Does It Matter?
Home equity is the difference between what your home is worth and what you owe on your mortgage. If your home is valued at $480,000 (the current Las Vegas median) and you owe $350,000, you have $130,000 in equity.
That equity is real wealth. You can access it through a home equity line of credit (HELOC) for renovations or major expenses. You can leverage it to buy an investment property. When you sell, it becomes cash in your pocket. Equity is the mechanism through which homeownership builds lasting financial security for families across the Las Vegas Valley.
Strategy 1: Pay Down Principal Faster
Every mortgage payment you make includes both principal and interest. In the early years of a 30-year loan, most of your payment goes to interest. The fastest way to build equity is to accelerate your principal payments.
Switch to biweekly payments. Instead of making 12 monthly payments per year, make 26 half-payments. This results in one extra full payment per year, which can shave 4 to 5 years off a 30-year mortgage and save tens of thousands in interest.
Round up your payment. If your monthly payment is $1,850, round it to $2,000. The extra $150 per month goes entirely to principal. Over a year, that is $1,800 in additional equity. Over 10 years, it is $18,000 plus the compound interest savings.
Apply windfalls to principal. Tax refunds, work bonuses, or gifted money from family can go directly toward your principal. Even a one-time payment of $5,000 can reduce your loan term by months and save thousands in interest.
Strategy 2: Make Smart, Value-Adding Improvements
Not every home improvement project builds equity equally. Some upgrades add substantial value to your home; others are purely cosmetic. In a balanced market, where buyers are selective, the right improvements can make your home stand out and command a higher price when it is time to sell.
Kitchen and bathroom updates offer the best return. Minor kitchen remodels recoup roughly 85 to 95 percent of their cost at resale in the Las Vegas market. Focus on countertops, cabinet hardware, lighting, and fixtures, not a full gut renovation.
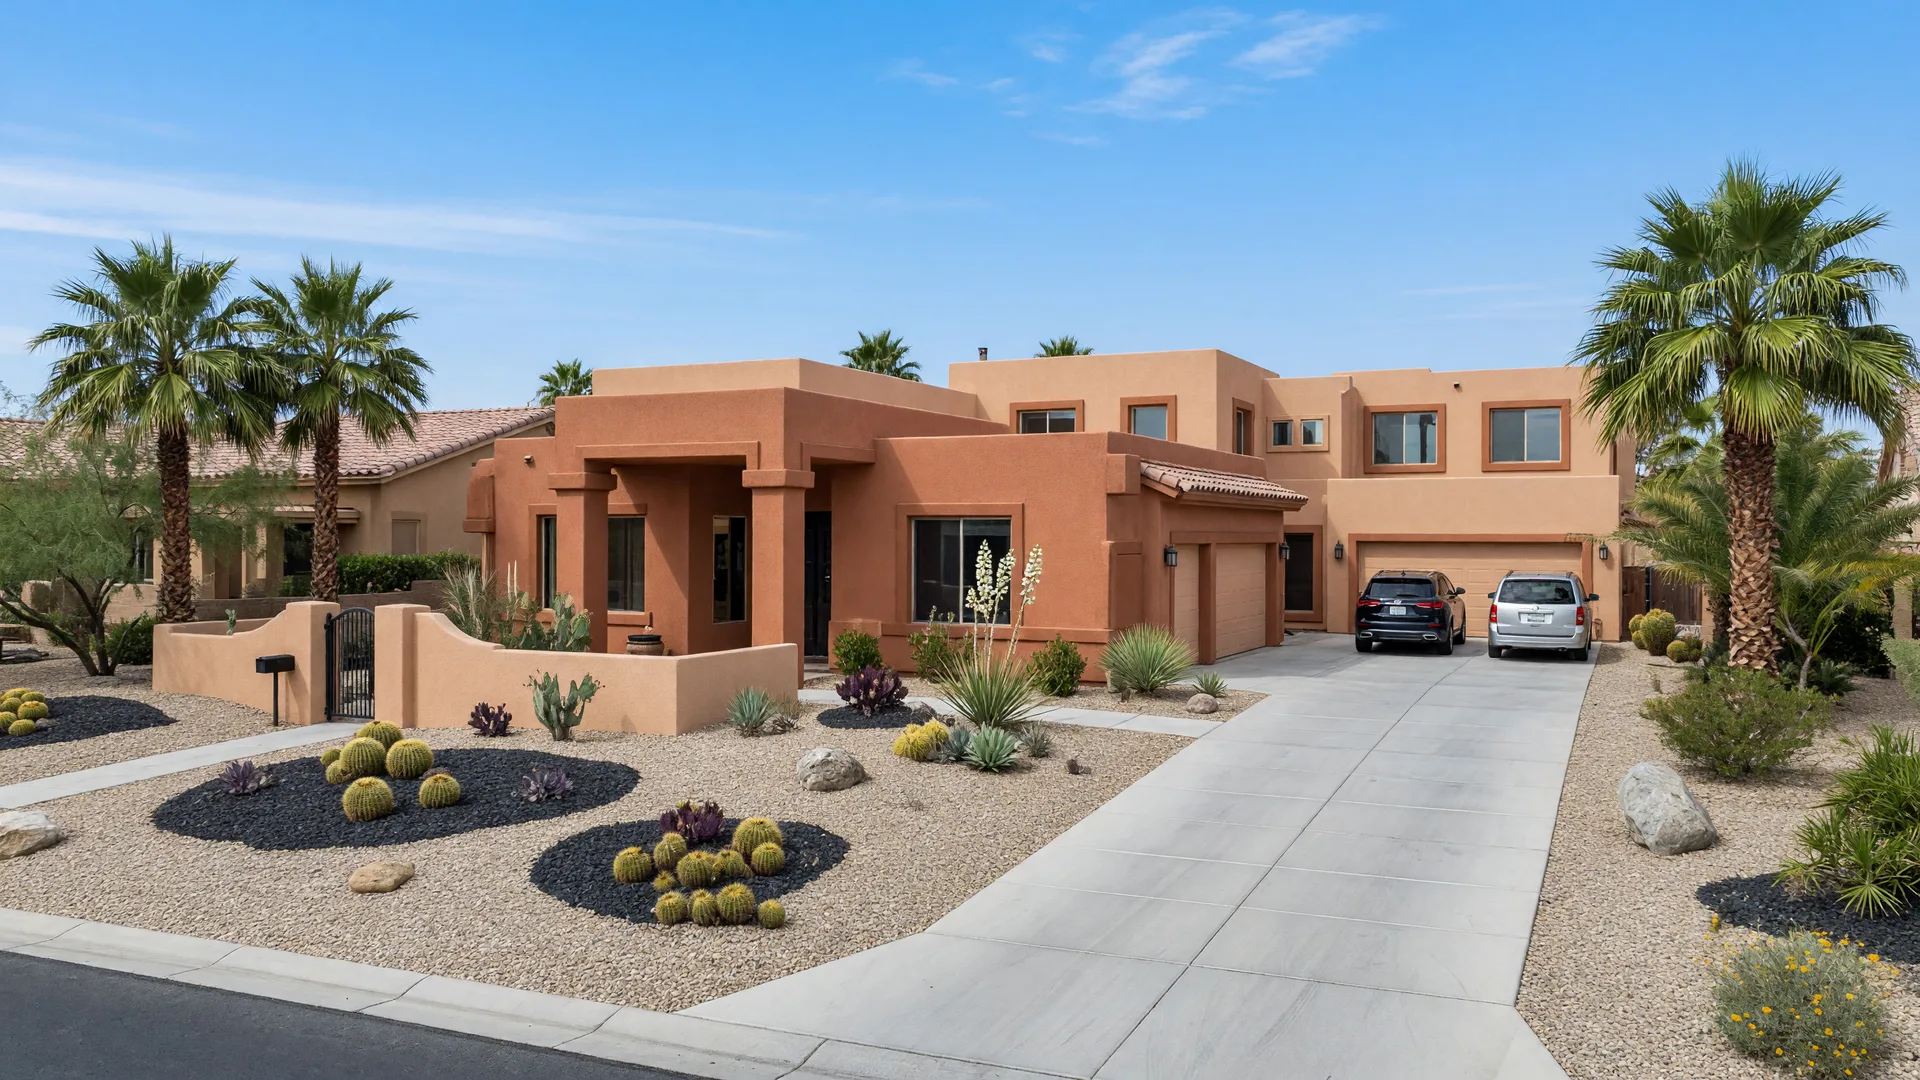
Desert landscaping adds real value. Xeriscaping with native plants, rock gardens, and drought-tolerant greenery is not only water-efficient but highly attractive to Las Vegas buyers. A well-designed front yard can add 5 to 10 percent to your home's curb appeal value.
Energy efficiency upgrades pay double. Solar panels, modern HVAC systems, and energy-efficient windows lower your monthly utility bills while increasing your home's market value. NV Energy offers rebates for qualifying upgrades that can offset your upfront costs.
Strategy 3: Leverage Nevada's Tax Advantage
One of the most overlooked equity-building tools is Nevada's tax structure. We have no state income tax. For homeowners who moved from California, Oregon, or other high-tax states, that savings can be substantial, often $10,000 or more per year.
Here is how that relates to equity. If you are saving $800 per month in state income taxes compared to your previous state, you can redirect that money toward your principal. That alone could add nearly $10,000 per year to your home equity. Over five years, with compound interest, that is more than $50,000 in additional wealth.
Nevada also has relatively low property taxes compared to the national average, with a cap on annual assessment increases. This keeps your carrying costs predictable and frees up more of your monthly budget for equity-building payments.
Strategy 4: Consider a Shorter Loan Term
If you bought your home when rates were low and have built some equity, refinancing to a 15-year or 20-year mortgage can dramatically accelerate your equity growth. Yes, your monthly payment will be higher. But a much larger portion of each payment goes to principal.
On a $350,000 loan at 6.5 percent, the principal portion of a 30-year payment in year one is roughly $350. On a 15-year loan at the same rate, it is roughly $1,500. That is more than four times the equity building per payment. If your budget allows, shortening your term is one of the fastest ways to own your home free and clear.
Strategy 5: Buy Now, Refinance Later
For first-time buyers or current renters thinking about entering the market, the most important equity strategy is simply to get in. Every month you pay rent is a month you build zero equity. Every month you pay a mortgage, you own a little more of your home.
Current mortgage rates at 6.63 percent are higher than the historic lows of 2021. But the path to wealth is not waiting for the perfect rate. It is buying at today's numbers, building equity from day one, and refinancing when rates eventually come down. The typical break-even on refi closing costs is 18 to 24 months, and if rates drop to 5.5 percent in that timeframe, you come out ahead.
The real cost of waiting. If you wait two years for rates to drop and home prices appreciate 3 to 5 percent in that time, you could pay $20,000 to $30,000 more for the same home. Meanwhile, the buyer who purchased today would have built $15,000 to $20,000 in equity through principal reduction and appreciation alone. Waiting costs more than most people realize.
Strategy 6: Use HELOCs Strategically
For homeowners with substantial equity, a home equity line of credit (HELOC) can be a powerful tool for building more wealth. The key is using it strategically. Using HELOC funds for home improvements that increase your property's value creates a positive cycle: the improvement boosts your home's worth, which grows your equity further.
Using HELOC funds to consolidate high-interest debt can also be a smart move, replacing 18 percent credit card interest with 8 to 9 percent HELOC interest. But I always caution against using home equity for lifestyle spending, vacations, or depreciating assets. Your home's equity is your financial foundation. Protect it.
A Note on the Current Market
The Las Vegas Valley market in August 2026 is balanced, with 3.6 months of supply and a median price of $480,000. Prices are not spiking, but they are not falling either. This stability is actually good for equity building. It means your home's value is on solid ground, and the equity you build through payments and improvements is real, not speculative.
For homeowners considering a sale, this balanced market means you can expect a fair price and a reasonable timeline. For those staying put, it means your equity is stable and growing with every payment you make. Either way, the fundamentals of homeownership as a wealth-building strategy remain as strong as ever.
The Bottom Line From Someone Who Has Lived It
I have been on my own since I was fourteen years old. I put myself through college as a single mother. I know what it means to fight for every dollar of financial security. And I know that for most families, home equity is the bridge between surviving and thriving.
Financial literacy is the foundation of everything I do with my clients. Whether you are buying your first home, selling to make your next move, or simply looking for ways to build more equity in the home you already own, I will meet you where you are. No judgment. No pressure. Just clear, honest guidance from someone who genuinely cares about your financial future.
The strategies in this article are actionable and proven. Pick one that fits your budget and start today. Your future self will thank you.
Whatever equity strategy you choose, watch the live market in your area. Browse current listings across every Las Vegas Valley ZIP on my live search: Search homes in the Las Vegas Valley.
Let us build a plan that works for you.
Whether you are ready to buy, thinking about selling, or want to explore how to maximize the equity in your current home, I am here to help. Reach out anytime for a straightforward conversation about your goals.