House hacking is the name for a simple, powerful idea: buy a home you actually live in, and rent out part of it to help pay the mortgage. In the Las Vegas Valley in 2026, with valley-wide median prices around $475,000 and rents still climbing, it is one of the most realistic paths for a first-time buyer to stop renting and start building equity. This guide walks through how house hacking works, the FHA math that makes it possible, and the neighborhoods across Henderson, Aliante, and the northwest where the numbers are worth running.
I believe homeownership is the most powerful wealth-building tool most families will ever get, and house hacking is the strategy that matches that belief with real numbers. It is not about becoming a professional landlord overnight. It is about buying your first home smarter, with rent from the other rooms or units helping you carry it while your equity grows underneath you.
What Is House Hacking, Exactly?
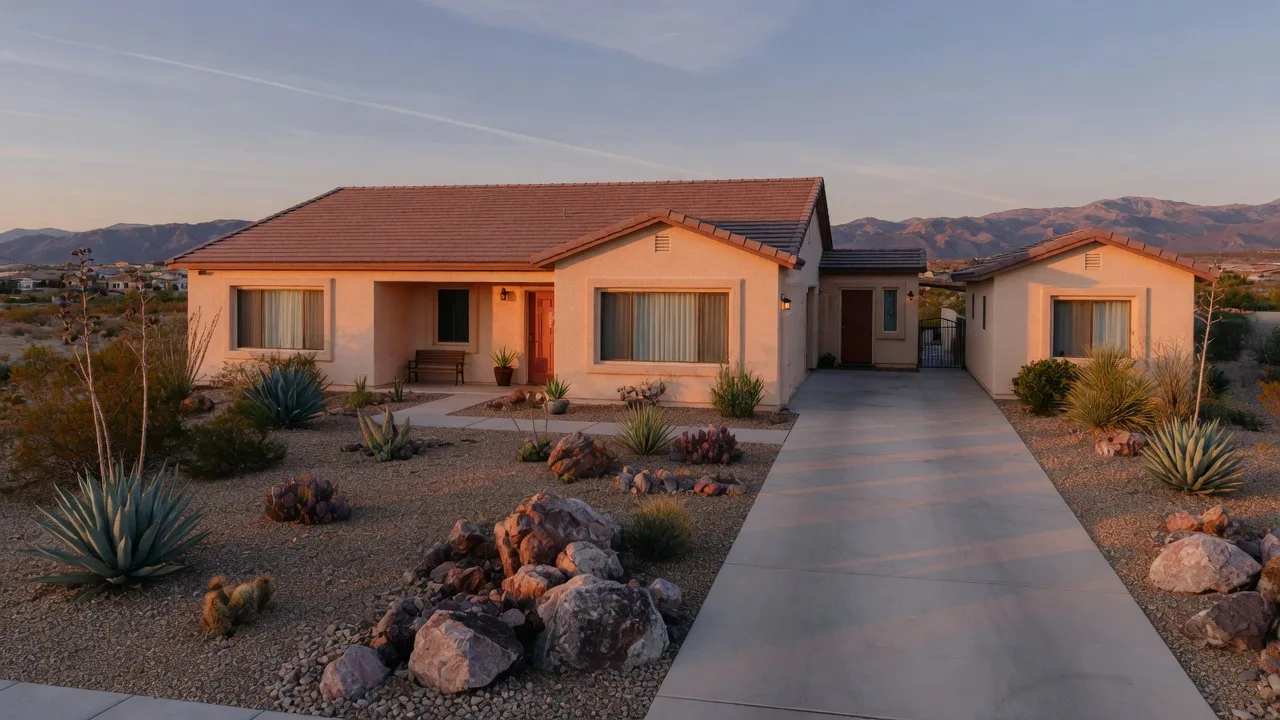
There are two main ways to house hack in Las Vegas. The first is to buy a duplex, triplex, or fourplex, live in one unit, and rent out the others. The second, and usually the more accessible here, is to buy a three- or four-bedroom single-family home and rent out the spare bedrooms, or rent a casita or accessory dwelling unit if the home has one. Nevada's new casita law, Assembly Bill 396, took effect in July 2026 and made accessory dwelling units easier to add, which means more single-family homes can generate rental income from a separate entrance. I covered the details in my full guide to the Nevada casita law.
The best part for first-time buyers: with an FHA owner-occupied loan, projected rental income from the units or rooms you are not living in can count toward your qualifying income. That is the mechanic that makes the whole strategy work on paper, not just in theory. You still have to live in the property, but your tenants help you qualify for it.
The FHA Math That Makes It Work
FHA loans are built for exactly this. You put 3.5% down with a credit score of 580 or higher, or 10% down if your score lands between 500 and 579. In Clark County, the 2026 FHA loan limit for a single-family home is $541,287, which covers most of the valley's entry-level inventory. If you want to step up to a duplex, the two-unit limit is $693,050, and for three- and four-unit properties it rises to $837,700 and $1,041,125 respectively. The catch, and it is an important one: you must occupy the property as your primary residence. House hacking is owner-occupied homebuying, not a workaround for absentee investing.
Henderson data from the Las Vegas REALTORS mid-2026 reports shows the city's median around $540,000, a premium of roughly 14% over the valley-wide median near $475,000. That premium reflects Henderson's parks, schools, and resale demand, but it also means the entry-level math is friendlier in communities where purchase prices sit closer to the valley average. The ZIP-level picture matters more than the citywide number, which is where a local agent earns their keep.
Rough Numbers on a Home Around $475,000
Let me show you the rough math, and I want to be upfront that this is ballpark, pre-tax arithmetic to illustrate the strategy, not a quote. On a $475,000 purchase with 3.5% down, the down payment is about $16,600 and the financed amount lands near $458,000. At the rates that have hovered in the mid-6% range through fall 2026, principal and interest run around $2,900 a month. Add property taxes, homeowners insurance, and HOA dues if the community has them, and the total payment typically lands in the upper-$3,000s depending on the ZIP.
Now the hack. In a three-bedroom home, renting out two bedrooms at the room rates typical across the valley, often $900 to $1,200 each, can offset a meaningful share of that payment. With a casita, the entire cottage rents at a higher rate than a single room. Federal fair market rent data for the Las Vegas-Henderson-North Las Vegas metro puts a three-bedroom unit around $2,400 a month, which tells you tenants are paying real money for this kind of space. The exact numbers depend on your property, your tenants, and your lender's underwriting, so treat this as the shape of the idea, then run the real numbers with your loan officer.
Where House Hacking Can Work: ZIP by ZIP
In Aliante (89084), single-family medians sit near $485,000, and the master plan's mix of standard homes and the 55+ Sun City Aliante section keeps a steady pool of renters looking for three-bedroom product. The 24-mile trail system and Aliante Golf Club make it an easy sell to young professionals renting rooms or a casita while they save for their own purchase. You can search homes in Aliante on my live portal to see current three-bedroom inventory in 89084.
Northwest Las Vegas offers similar value with strong rental demand. Providence (89131), Centennial Hills (89149), and Skye Canyon (89166) all have newer three- and four-bedroom homes with options for casitas or bedrooms that convert cleanly to rentals, and the proximity to the 215 makes them commuter favorites. View current listings in the northwest and filter by price point to see where the payment math gets comfortable.
In the southwest corner, Mountain's Edge (89178) is closing out its final new-home phases, which means resale three-bedrooms are becoming available in a community with 500-plus acres of parks and a regional park expansion underway. The core southwest ZIPs of 89113, 89141, and 89148 also hold newer product with rental-friendly floor plans. And in Henderson, the ZIPs worth screening are the family areas close to employment and the airport: Green Valley (89014 and 89074), the Green Valley Ranch and Anthem side (89012 and 89052), Inspirada (89044), and the downtown corridor (89015). Henderson's premium pricing means the hack is more about the casita or duplex path, but the rental demand is real, anchored by three-bedroom fair market rents near $2,400 metro-wide. Search homes in Henderson and we can screen for floor plans with a separate entrance.
One honest note about HOA communities: many Las Vegas master plans restrict full leases, while renting out a room inside your primary residence is treated differently. The rules vary community by community, so before you fall in love with a floor plan in 89178 or 89084, we read the association's CC&Rs together. It is a five-minute check that can save you from buying a home you cannot legally rent out.
The Rules That Keep a Hack Legal
The non-negotiables are worth repeating. You must live in the property for it to be owner-occupied, and lenders look for that intent. FHA loans carry mortgage insurance, so budget for that in the monthly math. You will also be responsible for county rental licensing and rental income tax rules once tenants move in, so pencil those in with your accountant. None of this is meant to scare you; it is meant to keep the strategy honest. When house hacking is done right, you are simply a homeowner who happens to have roommates, and the mortgage gets easier every year you stay.
Is House Hacking Right for You?
I will be honest with you the way I would want someone to be with me: house hacking asks something of you. It means sharing walls or a yard, handling an occasional maintenance call, and carrying the mortgage in the months between tenants. It is not for everyone, and deciding that is not for you is a completely valid answer. But if the idea of your tenants paying down your principal while you live in a home you own excites you, this may be the smartest first move you can make in this market. My job is to help you see the real numbers, not to push you into roommates.
Start where it is painless: browse current listings across the Las Vegas Valley on my branded search, and save the floor plans that catch your eye. Then we run the house-hacking math on the ones that fit.
Run the Numbers With Me
Let's see if house hacking is your path to homeownership.
Buying with rental income is a strategy, not a gimmick. I will help you compare ZIP codes, walk through realistic payment math, and connect you with lenders who understand owner-occupied first homes.