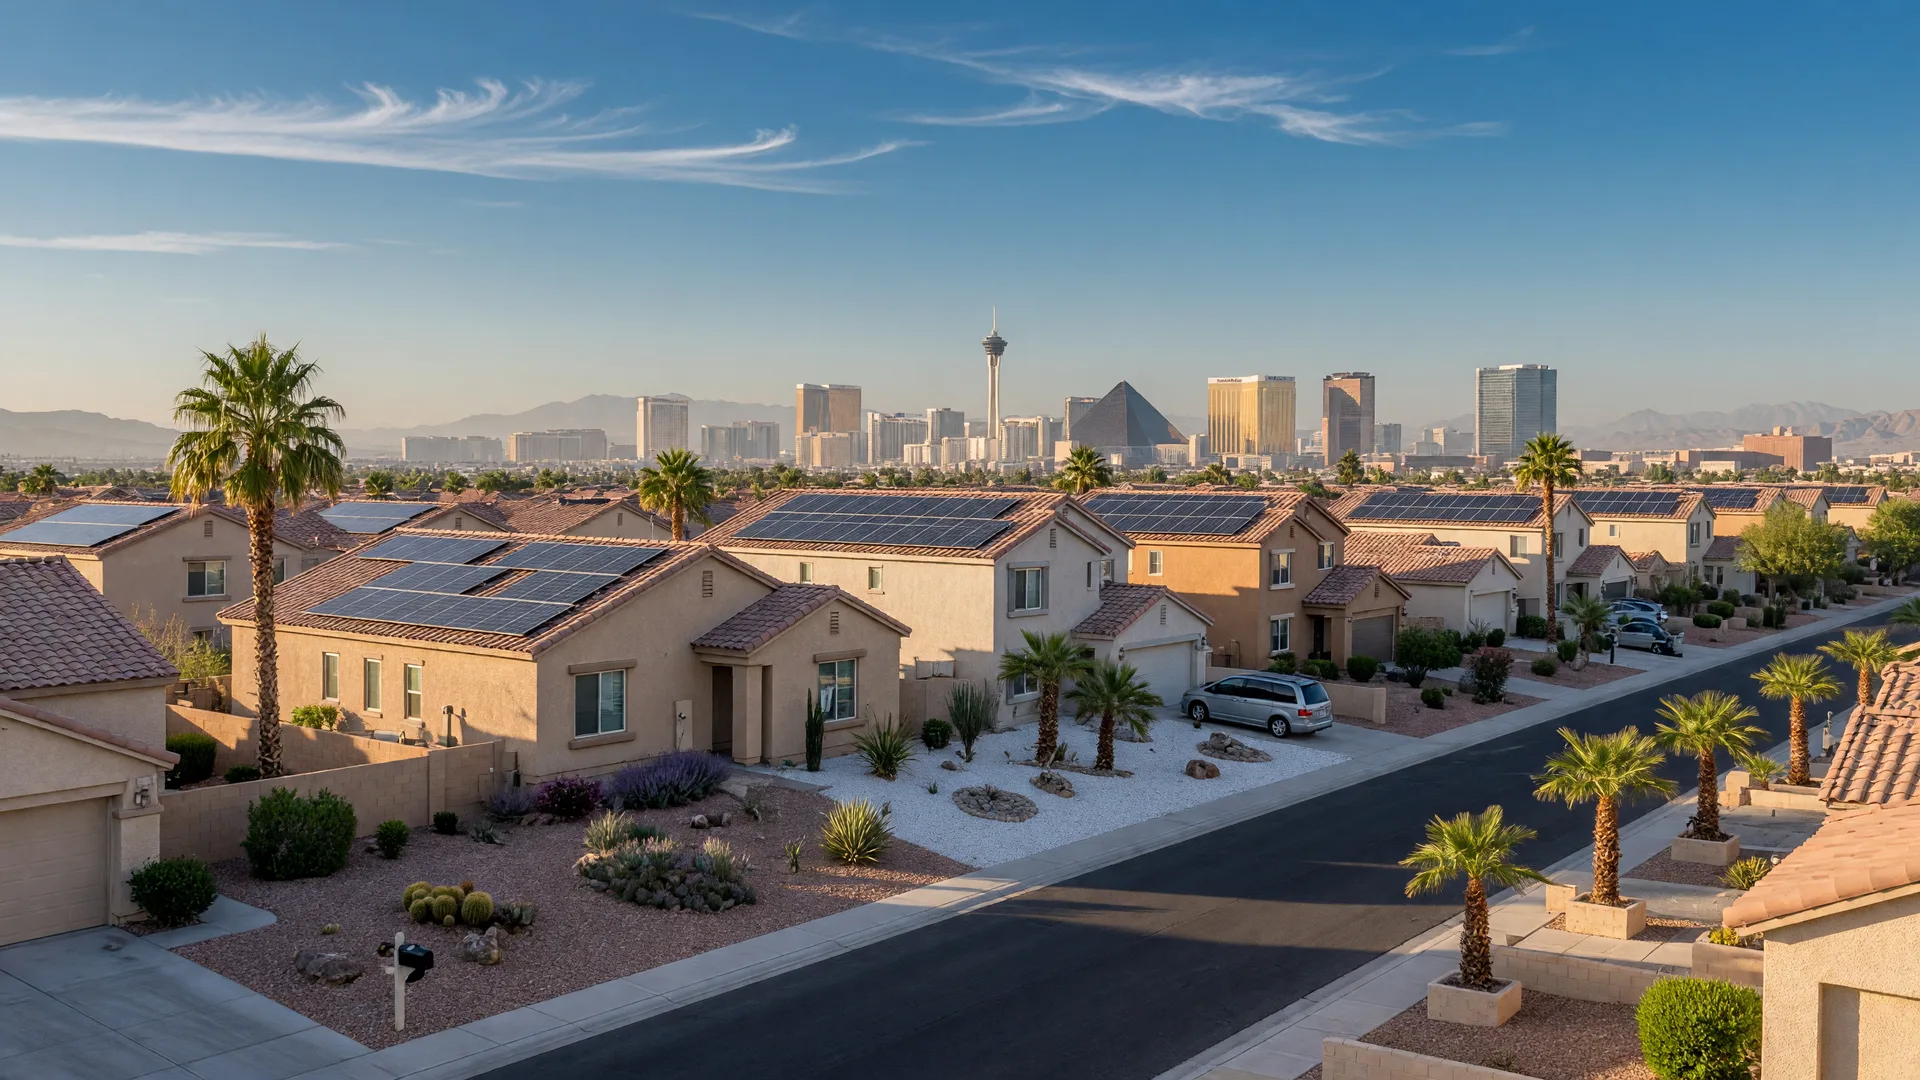
Heading into August 2026, the Las Vegas Valley real estate market is sending a clear message: we have entered a genuinely balanced market, one that rewards thoughtful strategy over impulse. The median home sale price held near $434,725 through late July, essentially flat compared to this time last year. Active inventory has rebuilt to approximately 15,141 homes across all property types, and the median days on market has stretched to about 30 days.
These numbers tell a story of stability, not weakness. But there is one variable that demands attention right now: mortgage rates are climbing again. The 30-year fixed rate has ticked up to about 6.7 percent, with some lenders now quoting closer to 6.9 percent as of early August. For anyone planning a move in the valley, understanding how these pieces fit together is the difference between making a confident decision and feeling stuck on the sidelines.
The $435K Plateau: What Flat Prices Actually Mean
At first glance, a year-over-year change of just +0.5 percent might look like the market is stalling. But context matters here. After the rapid appreciation of 2021 through 2023, when home values surged by double digits annually, a period of price stabilization is not a sign of trouble. It is the market catching its breath.
For buyers, flat prices mean you are not chasing a rising market. The home you look at today is likely to be priced similarly three months from now, which takes the pressure off making an immediate decision. For sellers, it means pricing strategy matters more than it has in years. Homes priced in line with recent comparable sales are still moving, but the days of automatic appreciation are behind us for the moment.
It is also worth noting that the valley-wide median masks meaningful differences between communities. Summerlin's median sits at approximately $686,000, reflecting a nearly 10 percent year-over-year increase driven by new construction and persistent demand. Henderson's median hovers around $540,000. Mountain's Edge and the southwest corridor offer more accessible entry points in the $430,000 to $470,000 range. The flat valley-wide number is partly a composition effect, with more lower-priced inventory pulling the median down even as premium communities continue to appreciate.
Inventory: The Biggest Change in the Market
The most significant shift in the Las Vegas Valley market over the past 12 months has been the recovery of inventory. With approximately 15,141 active listings, supply has returned to levels not seen since before the pandemic-era buying frenzy. This is the result of several factors working together: more homeowners choosing to sell after years of sitting on low-rate mortgages, an active new construction pipeline, and a gradual softening of demand as affordability constraints have limited how many buyers can qualify at current prices and rates.
For buyers, this is genuinely good news. You have options. You can visit multiple homes, compare neighborhoods, and take the time to make a decision based on fit rather than fear. For sellers, the message is equally clear: your home needs to stand out. Presentation, pricing, and marketing are no longer optional extras. They are the difference between a 30-day sale and a 60-day listing with price reductions.
New construction continues to be a significant driver of inventory. Builders across Summerlin, Henderson, Mountain's Edge, and Northwest Las Vegas are actively marketing new phases, and many are offering meaningful incentives to move units. Rate buydowns, closing cost credits, and design studio upgrades remain common. For buyers who are not finding what they want in resale inventory, new construction deserves a serious look.
Mortgage Rates: The 7% Threshold
Here is the variable that is shaping every decision in the market right now. The 30-year fixed mortgage rate has crept back up to approximately 6.67 percent in early August 2026, with some lenders pricing closer to 6.93 percent depending on the loan program and credit profile. To put that in perspective, we are now about 0.75 percentage points higher than the 2026 low point and approaching the levels that last challenged buyers in late 2023 and early 2024.
What does this mean for monthly payments? On a $435,000 home with 10 percent down and a 6.67 percent rate, the principal and interest payment is approximately $2,507 per month. At 6.93 percent, that same home costs about $2,561 per month. The difference of $54 per month may seem small, but when you compound it over 30 years, it adds up to roughly $19,000 in additional interest.
Since the spring 2026 low, the higher rate adds roughly $146 per month to the payment on a typical Las Vegas home purchase. For buyers, this reinforces the importance of negotiating seller concessions and rate buydowns.
The key insight here is not to panic over rate movements but to understand how they affect your personal numbers. A quarter-point increase adds roughly $60 to $70 per month for every $100,000 borrowed. If you are looking at a $470,000 home, a 0.25 percent rate increase adds about $60 per month. That is real money, but it is also manageable within most budgets. The more important question is whether you can comfortably afford the payment at today's rates — and whether a future refinance opportunity is realistic within your time frame.
Days on Market: A Measure of Balance
With the median days on market now at approximately 30 days, the Las Vegas Valley has settled into a tempo that feels genuinely balanced. In 2022, homes were selling in under 10 days. In 2023, that stretched to about 20 days. The 30-day mark is healthy — it gives buyers enough time to do their due diligence while signaling to sellers that prompt, strategic pricing is rewarded.
What I am seeing on the ground is a two-speed market. Homes that are priced correctly, staged well, and professionally marketed are still finding buyers within the first two to three weeks. Homes that are priced even 3 to 5 percent above market value are sitting for 40 to 60 days, often requiring a price reduction to generate activity. The spread between the best-priced listings and the overpriced ones has never been wider, and the difference in outcome is stark.
What Early August 2026 Means for Buyers
If you are a buyer in this market, here is my honest, education-first assessment: the conditions are some of the most buyer-friendly we have seen since 2018, and they may not last indefinitely. Here is what is working in your favor:
- More choices than ever. With 15,000-plus active listings, you can afford to be selective. Compare neighborhoods, tour multiple homes, and wait for the right fit.
- Seller concessions are the norm. Rate buydowns, closing cost credits, and repair allowances are all on the table. In a balanced market, sellers understand they need to compete for serious buyers.
- Builder incentives remain strong. New construction builders are offering 2-1 buydowns, closing cost assistance, and free upgrades to move inventory. If new construction fits your timeline, this is one of the best windows to buy.
- Down payment assistance is available. Nevada programs like Home Is Possible and Home At Last can provide up to $20,000 in assistance for qualified buyers. Do not assume you cannot buy just because your down payment savings are modest.
The main headwind for buyers is the rate environment. At 6.7 to 6.9 percent, monthly payments are stretched compared to where they were three years ago. The best strategy is to work with a lender who can run multiple scenarios — including buydown options — and to be realistic about your budget. If rates move lower in 2027, refinancing is always an option.
What Early August 2026 Means for Sellers
For sellers, the core message is this: the market is still healthy, but it requires more intentionality than it did two years ago. Homes that are priced correctly and presented professionally are selling at strong prices. Homes that are treated as a passive listing will sit.
- Price to the current comps, not last year's. In a flat market, using comparable sales from three to six months ago can lead to overpricing. I recommend studying what is selling today in your immediate neighborhood and pricing within that range.
- Invest in professional presentation. With more inventory, buyers are comparing your home directly against five to ten others. Professional photography, minor staging, and curb appeal improvements are not optional. They are the price of admission.
- Be prepared to offer concessions. A rate buydown or closing cost credit can make your listing stand out. Building a $6,000 to $10,000 concession into your pricing strategy from day one is more effective than reacting after 40 days on market.
What This Market Means for Homeowners
If you are not planning to buy or sell right now, the August 2026 data still matters to your financial picture. Your home equity is stable. The median home price in the valley has held above $430,000 for over a year, which means homeowners who purchased before 2022 are sitting on substantial equity gains. Even buyers who purchased at the peak of the market in 2022 have likely seen their values hold steady, if not appreciate slightly.
The question I encourage every homeowner to ask is: are you making the most of that equity? Whether it is through a HELOC for home improvements, a refinance if it makes sense for your situation, or simply knowing that your net worth is on solid ground, understanding your home's value in the current market is financial literacy in action.
Looking Ahead: What the Second Half of 2026 May Bring
The consensus among analysts tracking the Las Vegas market is that the remainder of 2026 will be defined by stability rather than dramatic movement. Prices are expected to remain flat to slightly up, with annual appreciation in the 1 to 4 percent range depending on the neighborhood. Inventory will likely continue to grow, especially as new construction deliveries absorb current demand. Mortgage rates will remain the wild card, with the most likely scenario being a range of 6.2 to 6.8 percent through the end of the year, depending on Federal Reserve policy and economic data.
The most important variable that no one can predict with certainty is the election cycle effect. The November 2026 midterm elections are likely to create some uncertainty in consumer confidence, which could slow market activity in October and November. Historically, real estate markets tend to slow slightly during election seasons, then recover in the months following. If you are planning a move, the August-through-September window offers a sweet spot before the election noise.
The Bottom Line
The Las Vegas Valley market in early August 2026 is defined by balance. Prices are stable. Inventory is healthy. Days on market are reasonable. Mortgage rates are a challenge, but they are not insurmountable — especially when you factor in the seller concessions, builder incentives, and down payment assistance programs available right now.
The question that matters most is not whether the market is good or bad. It is whether you have a clear picture of how today's conditions apply to your specific situation. Every neighborhood, price band, and transaction is different. A first-time buyer with $20,000 in down payment assistance available has a completely different set of opportunities than a move-up buyer trading into Summerlin. That is where personalized, data-driven guidance makes the difference between feeling stuck and moving forward with confidence.
I track these numbers every week because the data tells a story, and every client deserves to understand that story before making one of the biggest financial decisions of their life. Whether you are buying, selling, or just trying to understand where you stand, I would love to walk through the numbers with you. No agenda, no pressure — just real answers and a plan that makes sense for you.
The areas doing the most heavy lifting this August are Summerlin (89135, 89138, 89144), Henderson (89002, 89012, 89014, 89015, 89044, 89052, 89074), Mountain's Edge (89178), and the Northwest (89129, 89130, 89131, 89149, 89166). See what is listed in each on my live search: Search homes in the Las Vegas Valley.
Your next move deserves a clear-eyed, data-driven plan.
Whether you are looking to buy your first home, sell your current property, or just understand how the market affects your financial picture, I will give you an honest assessment based on the latest Las Vegas Valley data. No sales pitch, just real answers.